

Every UK founder preparing to raise eventually opens their data room to a stranger's scrutiny, and what they find decides whether the round moves forward or not.
UK startups and scaleups raised $23.6 billion in venture capital in 2025, a 35% increase on 2024 and the first annual growth in four years (HSBC Innovation Banking UK / Dealroom, 2025 UK Innovation Review), meaning more founders than ever are about to be read critically for the first time ever.
From cap table red flags to undisclosed litigation, the due diligence red flags below are the specific, recurring data room red flags that make an investor pause, ask harder questions, or walk each fixable before the room is shared.
Messy or Inconsistent Cap Tables
A cap table becomes one of the clearest cap table red flags the moment ownership percentages in a pitch deck don't match the underlying share register.
Investors read a cap table to model dilution and exit returns, and any gap between deck and register breaks that model instantly.
The usual culprits are mundane: an option granted verbally but never documented, or a converted ASA that wasn't updated everywhere, still one of the due diligence red flags an associate will spot within the first hour, costing weeks the round doesn't have.
Missing IP Assignment Agreements
Under UK law, an employer automatically owns copyright created by an employee in the course of employment, but that default doesn't extend to contractors (section 11(2), CDPA 1988), one of the most common IP assignment issues facing an early-stage UK startup.
A freelance developer who built the MVP owns that work unless there's a separate written assignment, valid only if signed by the assignor (section 90(3), CDPA 1988).
The same principle runs through the Patents Act 1977 for employee inventions, if nobody signed anything, the company may not own what it's raising money against.
Unresolved Related-Party Transactions
A related-party transaction is any deal between the company and someone with a pre-existing close relationship to it - a director, a family member, or a business they control.
Under FRS 102 Section 33, UK companies must disclose material related party transactions in their financial statement notes, because these deals may not be struck at arm's length. Investors watch for one pattern above all: revenue routed through a founder's other company, or a "customer" that's actually a connected party inflating traction.
There's a legal backstop too - under section 190 of the Companies Act 2006, a director acquiring or disposing of a substantial asset (over the lower of £100,000 or 10% of net asset value) needs shareholder approval, not just a board nod.
Numbers That Don't Reconcile Across Documents
Numbers that don't reconcile - an ARR figure in the deck that doesn't match the signed contracts in the room - are among the fastest due diligence red flags to trigger real investor doubt. Diligence findings are now the leading cause of broken deals across the wider M&A market: non-QoE diligence findings accounted for 25.3% of failed transactions in 2025, and quality-of-earnings discrepancies a further 21.3% (Axial, Dead Deal Report 2025).
That data covers the broader business-sale market rather than early-stage UK fundraising specifically, but the mechanism holds either way.
Disorganised or Incomplete Data Room Structure
A disorganised data room is one of the fastest data room red flags to spot - an investor forms an impression before reading a single document.
A folder structure that buries basics signals, fairly or not, that the same disorganisation runs through the business.
Unlike the gaps above, this isn't a legal defect, just a first impression entirely within a founder's control to fix. Grouping documents into clear categories (Corporate & Legal, Financials, Cap Table, Product, Team) does more for investor confidence than any single document inside it.
Outdated or Stale Financials
UK private limited companies must file annual accounts with Companies House within nine months of year end, and missing that deadline triggers an automatic, escalating penalty:
- Up to 1 month late: £150
- 1–3 months late: £375
- 3–6 months late: £750
- More than 6 months late: £1,500 (doubled to a maximum £3,000 if late two years running)
(GOV.UK)
The confirmation statement works differently, and there is no automatic banded fine, but Companies House can issue a discretionary penalty of up to £5,000 and begin strike-off proceedings for non-filing (GOV.UK).
Investors check both registers early, and stale financials are an easy due diligence red flag to spot.
Missing Board Approvals for SAFEs or Option Grants
UK startups more commonly use an Advance Subscription Agreement (ASA) or convertible loan note than a US-style SAFE, and both need board approval before signing.
For SEIS-qualifying ASAs, HMRC requires conversion into shares within six months, or the round risks losing SEIS eligibility. EMI option grants are equally tight: once HMRC agrees a valuation, the company has 90 days to grant options at that price, and grants made from 6 April 2024 onward must be notified to HMRC by 6 July following the tax year's end, or lose their tax-advantaged status.
A missing board minute here is one of the quickest gaps for an investor to spot.
Undisclosed Litigation or Regulatory Exposure
Any pending litigation, regulatory investigation, or contractual dispute left out of the data room reads to investors as concealment, not oversight - one of the more serious due diligence red flags, since it signals a founder managing the narrative rather than the business.
Directors carry a general statutory duty under the Companies Act 2006 to act in the company's interests, extending to disclosure.
A founder who volunteers a resolved dispute reads as trustworthy; one whose room stays silent reads as the opposite.
Customer Contracts That Don't Match Revenue Claims
When the ARR figure in a pitch deck is higher than the signed customer contracts actually total, investors ask where the difference comes from before anything else, it's one of the simplest checks in the process.
A gap explained by genuine invoicing timing is recoverable; a gap with no clear explanation reads as a founder managing the story rather than the business.
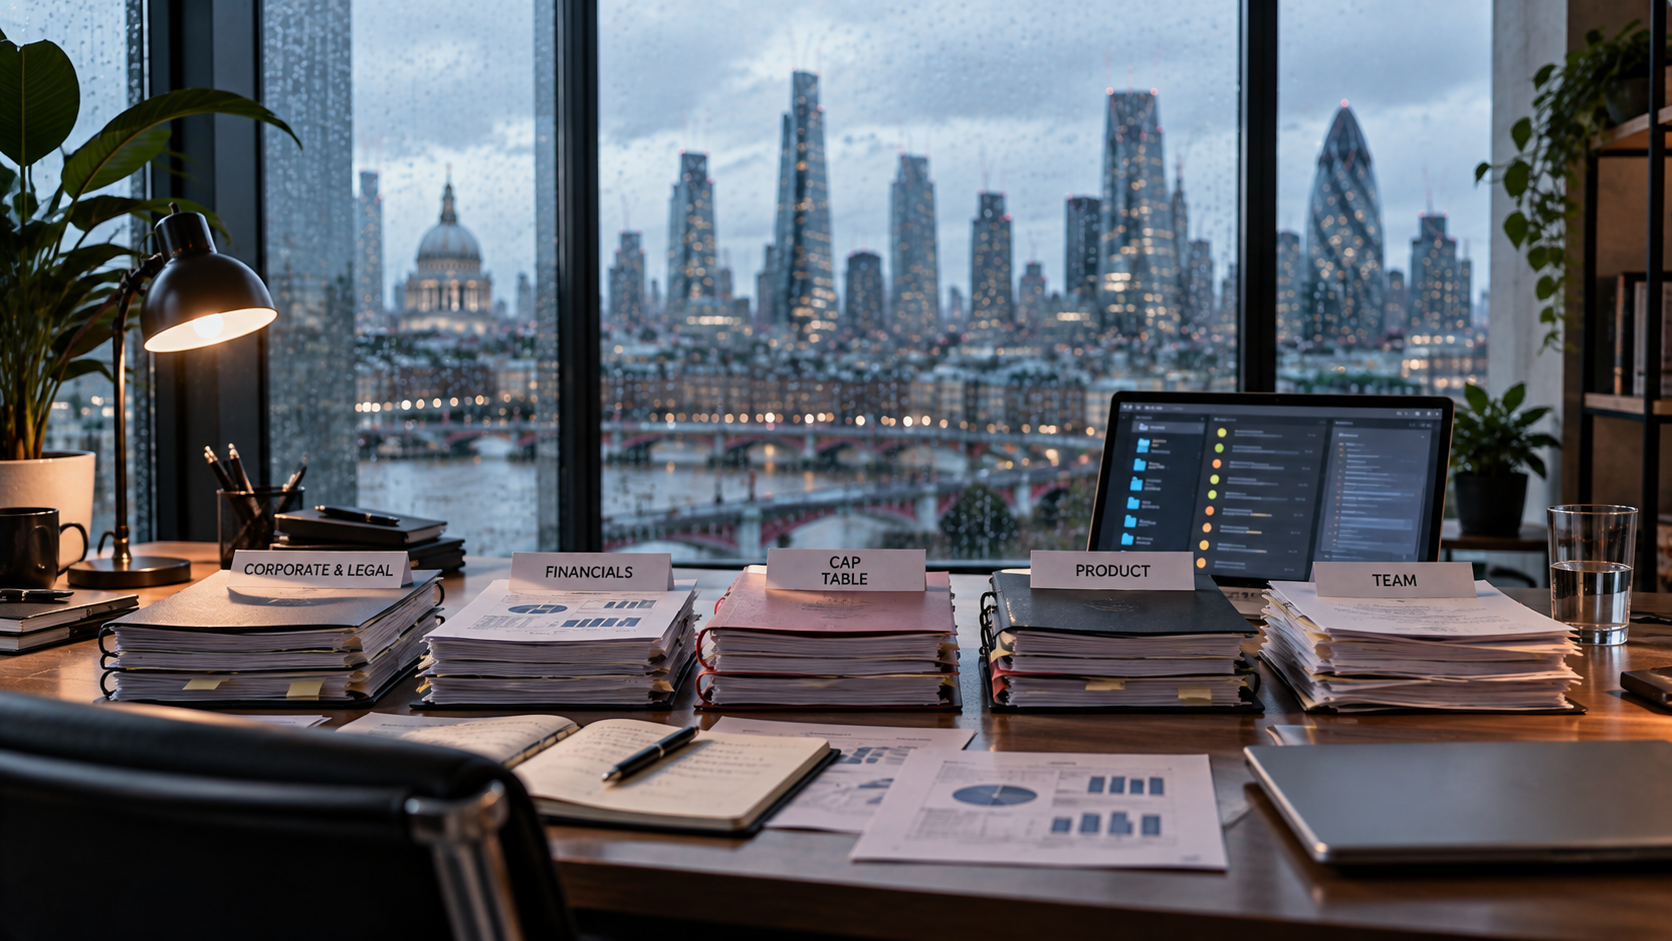
A Data Room Built Reactively, Only After Investors Ask
A data room built only after an investor asks for one is assembled under pressure, and it shows- missing documents, inconsistent formatting, questions it fails to anticipate.
The pressure to be ready earlier is measurable: HMRC's own figures show advance assurance approvals getting harder to secure, with EIS rates falling from 76% of applications in 2024–25 to 72% in 2025–26, and SEIS from 85% to 76% over the same period (HMRC, Enterprise Investment Scheme and Seed Enterprise Investment Scheme: 2026).
Preparing early is the difference between diligence confirming confidence and diligence manufacturing due diligence red flags out of unpreparedness.
Cap table red flags and disorganisation are the fastest to spot, often within minutes.
Related party transactions take longer to surface, worth flagging to advisors before a room opens, either way, the data room red flags an investor finds first rarely kill a deal outright, they cost a founder the benefit of the doubt for everything after.
FAQs
What is an IP assignment agreement and why does it matter to investors?
It's the written document transferring ownership of intellectual property - typically copyright or patents - from creator to company. UK default rules are narrower than most founders assume: contractors own what they build unless there's a signed IP assignment (CDPA 1988, s.90(3)), so without one, the company may not legally own its own product.
What counts as a related party transaction in a startup?
Any transfer of resources or services between the company and someone with a pre-existing close relationship — a director, a family member, or a business they control. Under FRS 102 Section 33, UK companies must disclose material related-party transactions in their accounts; under Companies Act 2006 s.190, a director buying or selling a substantial asset needs shareholder approval, not just board sign-off.
What happens if a startup fails investor due diligence?
The round typically stalls while the specific due diligence red flags get resolved, gets re-priced if the issue touches the valuation, or the investor walks if the gap is serious. Diligence findings are the leading cause of broken deals across the wider M&A market (Axial, 2025).
Also read: What the UK Maritime Innovation Hub Reveals About Britain's Maritime Tech Bet
Sources: HSBC Innovation Banking UK/Dealroom (2025 UK Innovation Review); CDPA 1988; Patents Act 1977; Companies Act 2006; FRS 102 §33; GOV.UK (Companies House penalties, EMI options); HMRC (2026 EIS/SEIS statistics); Axial (2025 Dead Deal Report).
The EP+ Editorial Desk covers UK startups, founder stories, and venture capital. All content is independently produced and human-reviewed before publication.


