

A regulator built a fast lane for UK maritime tech startups. We looked at whether the UK Maritime Innovation Hub is actually shrinking the gap between prototype and commercial deployment, or just moving where founders get told no.
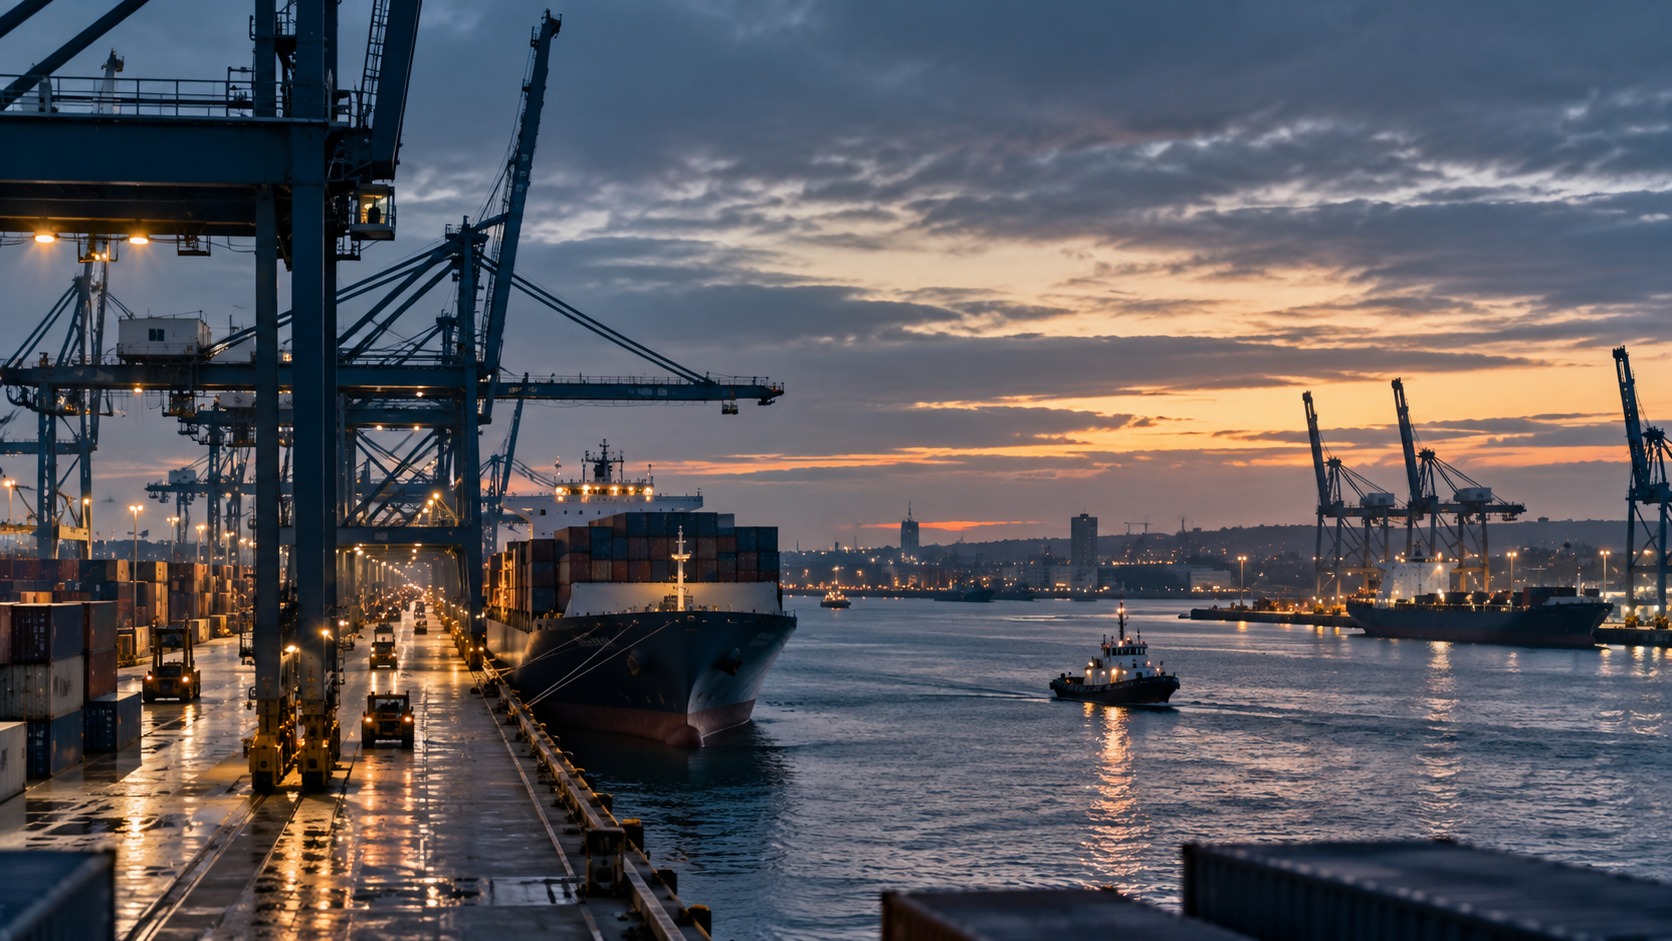
Shipping moves roughly 90 percent of world trade and gets almost none of the startup attention its trade volume would actually suggest. Ports are the physical chokepoints where that trade actually changes hands, and get even less.
It is one of the last major pieces of British infrastructure that has not been meaningfully rebuilt by software, and the reasons for that are the same reasons that make the sector interesting to us now, with heavy capital requirements, long commercialisation timelines, and a regulatory environment built around safety-critical physical assets rather than iterative product releases.
In April this year, the Maritime and Coastguard Agency tried to do something about that part, and finally launched what would become the UK Maritime Innovation Hub.
The Regulatory Bet
The UK Maritime Innovation Hub was formally showcased at the UK Flag Forum in London on 16 April, and launched properly on 9 June. It is not an accelerator, a fund, or an industry body, it is a single point of contact inside the MCA itself, built to give UK maritime tech startups, shipowners and operators a coordinated route through regulatory approval across four priority areas which are maritime autonomy, decarbonisation, digital systems, and nuclear propulsion.
It is also, notably, the primary contact point for vessel trials in Plymouth Harbour, and it has already been supporting applicants to two live government funding competitions, namely, the Clean Maritime Demonstration Competition and the Zero Emission Vessels and Infrastructure scheme.
“This is an exciting time to be a part of the maritime industry.” — Lars Lippuner, MCA Director of UK Customer Maritime Services
We think this is worth taking seriously precisely because it might be unglamorous now but absolutely worth it.
The UK Maritime Innovation Hub does not write cheques, but what it does is address the specific failure mode that tends to kill physically intensive startups before they reach commercial scale: the gap between a working prototype and something a regulator will actually let onto the water.
That exact gap, in climate tech and defence tech alike, has proven to be where well-funded companies quietly stall.
A regulator building dedicated capacity to shorten it is a structural intervention, not a funding announcement, and it is the kind of decision that only shows up in outcomes eighteen months later.
Three months after formal launch, the MCA reported steadily increasing enquiry volume through the UK Maritime Innovation Hub, with early interest concentrated in decarbonisation, followed by autonomy and digital systems.
That is an engagement metric, and not a funding metric.
We do not yet know whether faster regulatory pathways translate into more UK maritime tech startups reaching commercial deployment, or simply into more of them reaching the point of rejection faster.
Where the Capital Is Actually Going
The funding picture is smaller and more uneven than the regulatory story suggests, and it leans heavily on the state.
UK ocean tech startups have raised a combined $479 million over the past decade, according to Tracxn, the second-highest total globally behind the United States and well ahead of China.
Roughly 309 UK companies sit within the sector as tracked. That right there is a real number, but a small one relative to other UK sectors, and it has been raised gradually rather than in a recent surge.
Non-dilutive government funding tells a different story.
The Clean Maritime Demonstration Competition alone has committed close to £160 million across six rounds since its launch, with a seventh round now open offering between £750,000 and £15 million per project, and a total pot of £121 million.
That is a meaningful multiple of the UK's total decade of private investment in UK ocean tech startups, concentrated into a single recurring grant programme. For founders in this sector, the government is not a complement to venture capital.
In several of the case studies we looked at, it is the primary funder.
Globally, 2026 has seen a sharp jump in maritime and ocean tech funding, with Tracxn recording $1.96 billion across 16 rounds year-to-date against $690 million in the same period last year.
We would flag this figure carefully rather than present it as evidence of a UK boom: the majority of that global total is a single US maritime autonomy round. The increase among UK maritime tech startups specifically, where it exists, looks structural and grant-led rather than a reflection of the same venture enthusiasm reshaping the market elsewhere.
Worth noting too: maritime as a category attracts only around 0.3 percent of total global VC investment, against roughly 0.9 percent of global GDP, according to analysis from pH3 Capital Ventures and Maritime UK, a disproportion that sits underneath every funding figure in this piece.
“...there’s a clear requirement for more” [investment]. — Anjali Bakhru, Co-Founder, pH3 Capital Ventures
Four Companies Building Inside That Gap
Seabound, a London-based marine carbon capture company founded by Alisha Fredriksson in 2021, secured a £1.1 million CMDC grant this year to integrate its technology into the Port of Southampton, working alongside Associated British Ports and STAX Engineering.
The project builds on what the company describes as the world's first port-based CO₂ capture demonstration, run earlier at the Port of Long Beach. It is a useful illustration of a pattern common across UK ocean tech startups: proving out infrastructure-level deployment at a British port using a government grant, rather than raising that stage of validation from private capital.
Zelim, based in Edinburgh, builds unmanned search-and-rescue technology, including what it describes as the world's first remotely operated rescue vessel, it raised £2.3 million from Kero Development Partners and Aberdeen-based I7V, following an initial 2020 seed round, and has drawn additional support from the Offshore Wind Growth Partnership. Its route to market has run through the offshore energy sector rather than commercial shipping directly, which is itself telling about where early revenue is currently easiest to find.
Rovco, based in Bristol, builds AI-driven subsea inspection technology, applying real-time 3D vision to underwater survey work that has traditionally required expensive manned operations. It sits alongside companies like Savvy Navvy and Vaarst among the more visible names inside the UK Maritime Innovation Ecosystem, in a sector Tracxn tracks at 309 UK companies but where genuinely well-known consumer-facing names remain rare.
Spot Ship represents the fourth pillar the UK Maritime Innovation Hub covers on paper but that our earlier research had missed in practice: shipping logistics software.
It was founded in London in 2019 by James Kellett, the company uses AI and machine learning to cut the ship chartering process, traditionally a multi-day exercise involving fragmented manual data, down to a matter of hours, and it raised £1 million in a seed round led by the Lisbon-based fund Ventures.eu in January 2026, with participation from Improbable CEO Herman Narula.
Unlike the other three companies here, Spot Ship's route to relevance runs entirely through private venture capital rather than government grants, which makes it the clearest counter-example to the pattern the rest of this piece describes.
What We're Still Watching
The honest picture is that the UK Maritime Innovation Ecosystem is quite infrastructure-heavy and grant-dependent, at an early stage of whatever transformation is coming.
The UK Maritime Innovation Hub is just five months old, and we do not know yet whether it meaningfully shortens the path from prototype to deployment, or whether the UK maritime tech startups passing through it convert that regulatory clarity into private investment afterwards.
We are also currently watching whether the current concentration of capital in decarbonisation and autonomy leaves other parts of the UK Maritime Innovation Ecosystem underfunded, the same pattern we have seen play out in UK climate tech, where adaptation and food systems technologies remain structurally starved of capital relative to their importance.
Since port digitisation specifically still looks more like incumbent territory than startup territory in the UK, the Port Community Systems running customs and cargo data at major British ports are largely operated by established players like DP World's CNS, not venture-backed newcomers.
Whether that changes, and whether Spot Ship's private-capital route proves more replicable than Seabound's or Zelim's grant-led one, is a question we would like to put directly to founders working inside the UK Maritime Innovation Hub's four priority areas.
Also read: UK EdTech Companies Now Bet on Grants Before Venture Capital
Sources: Maritime and Coastguard Agency (GOV.UK) · Tracxn Maritime Tech UK sector data · Maritime Research and Innovation UK · TradeWinds · Seedtable · Hellenic Shipping News · offshoreWIND.biz · Maritime UK / pH3 Capital Ventures · SAFETY4SEA · Seatrade Maritime · tech.eu


